The Math
Is an HSA worth it?
Most people want to know whether an HSA is worth the effort. Here's the math, and it works no matter how much you're able to contribute.
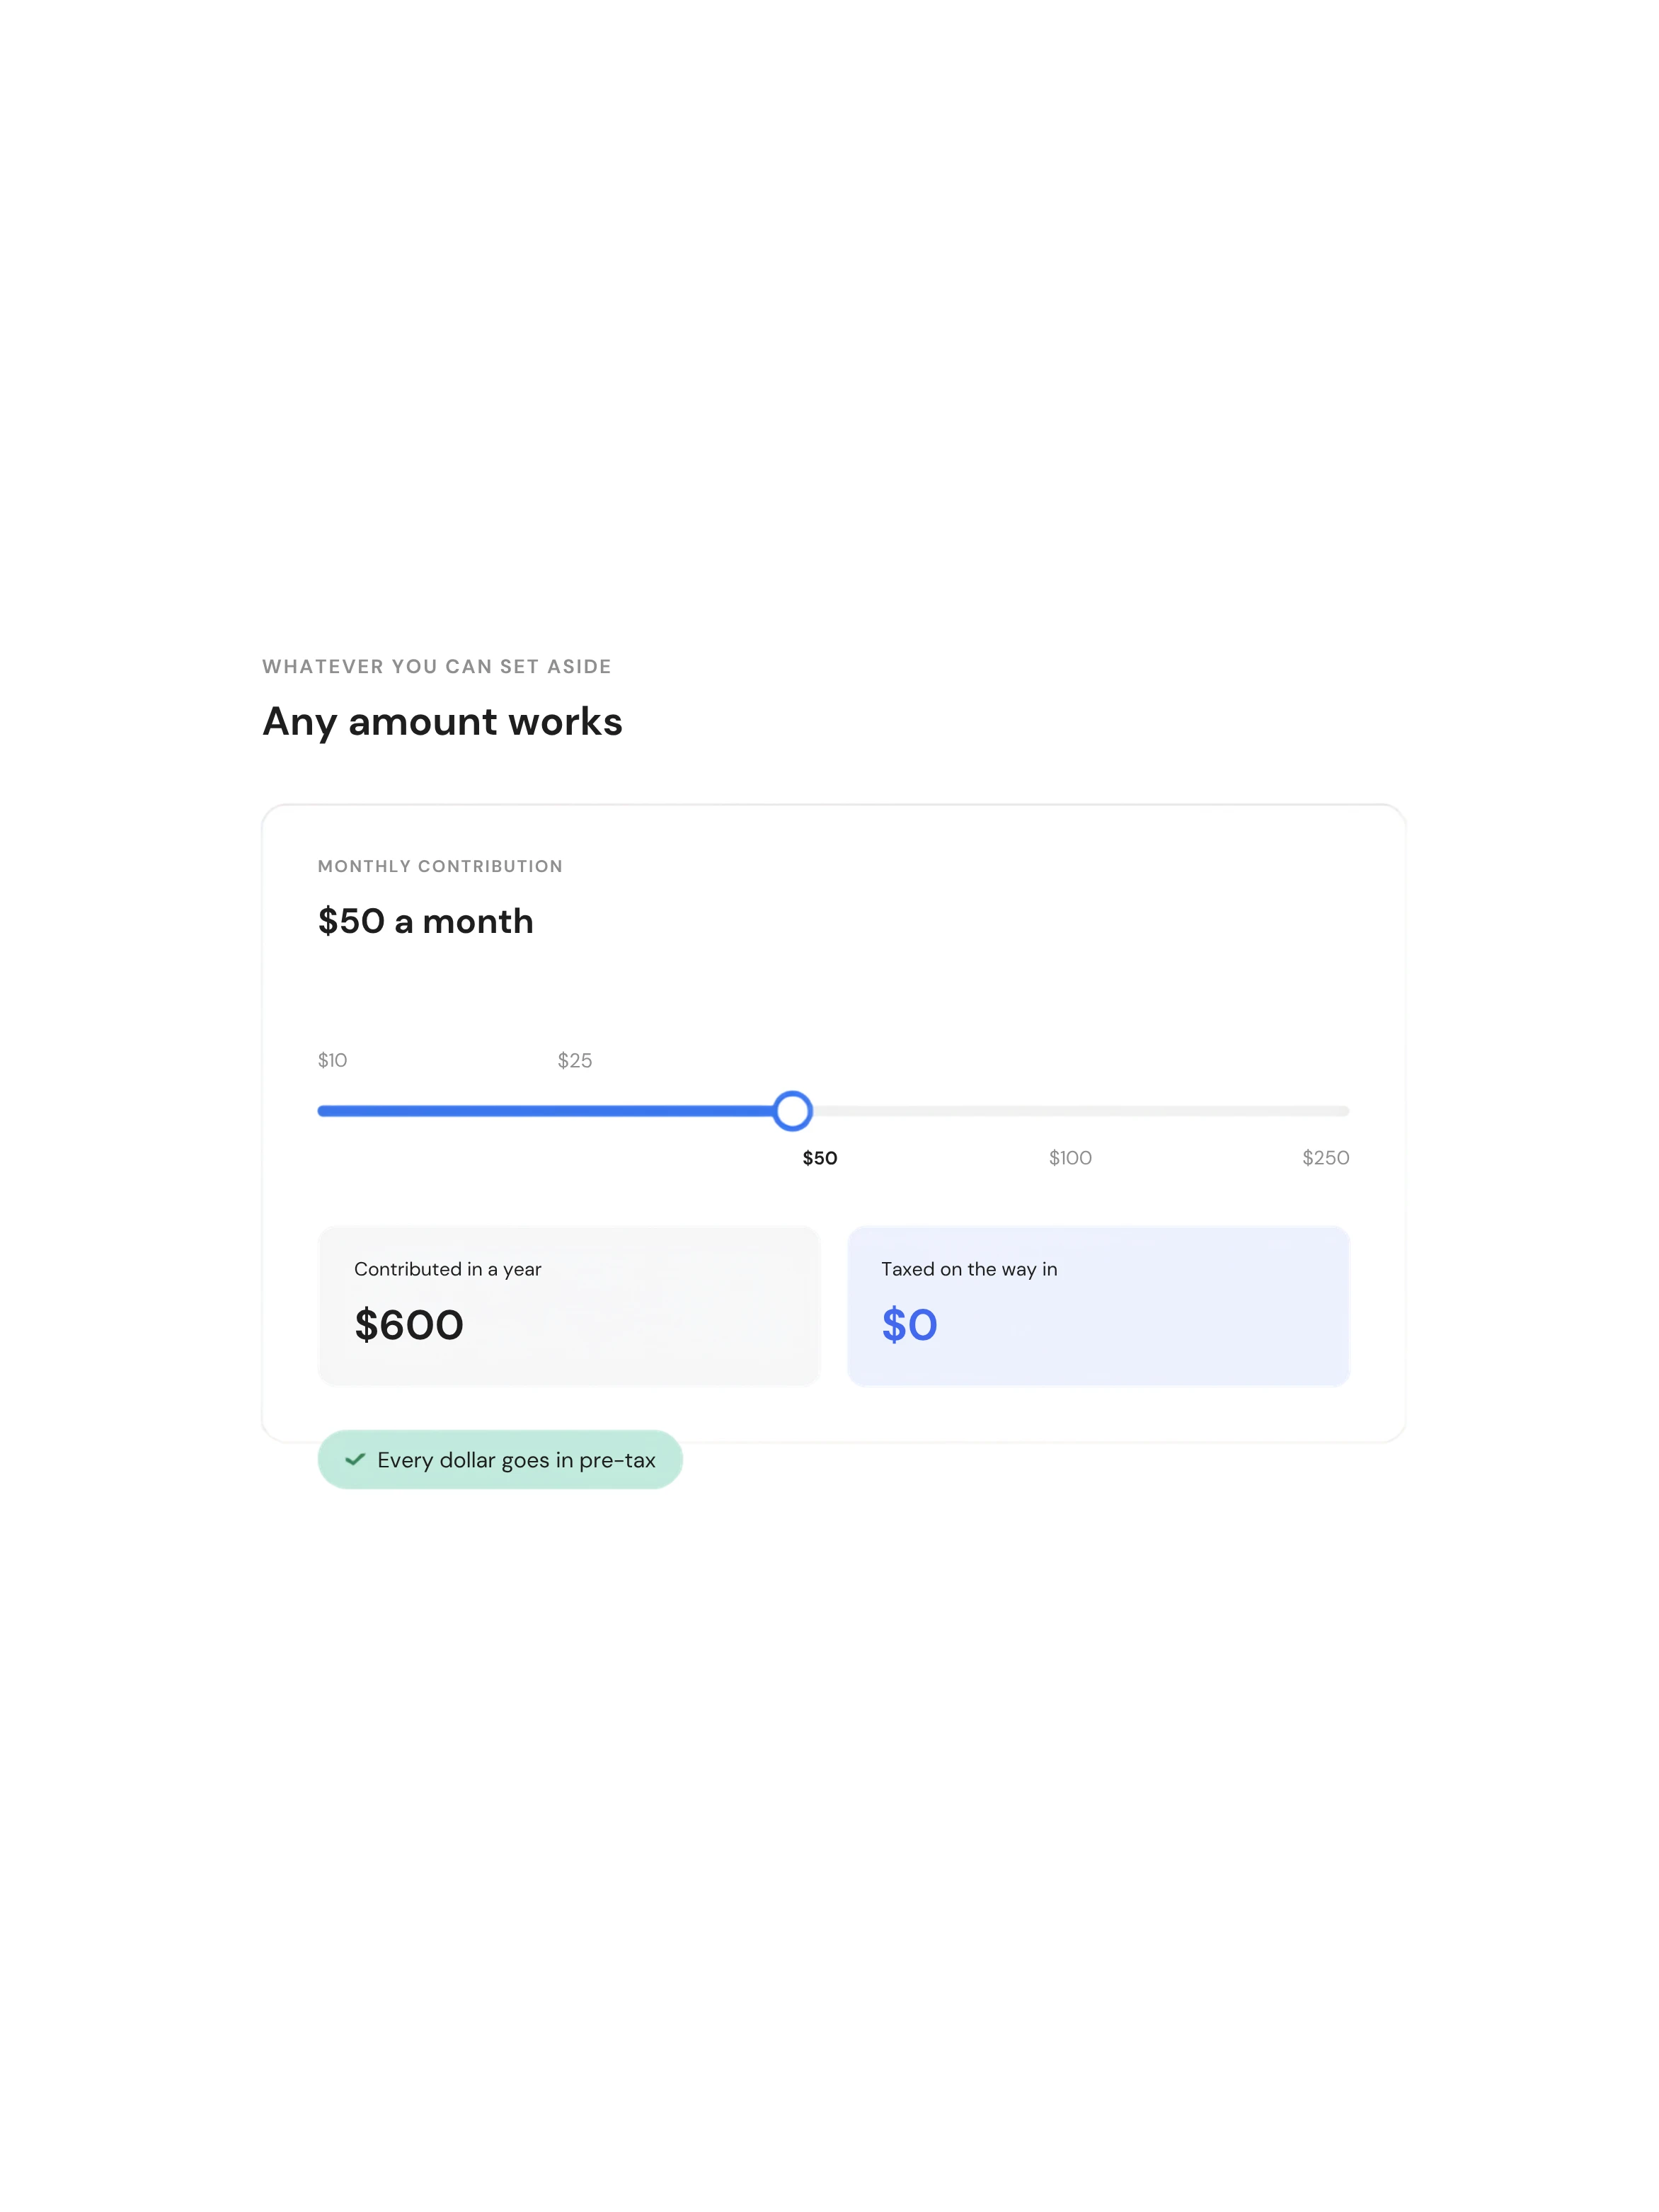
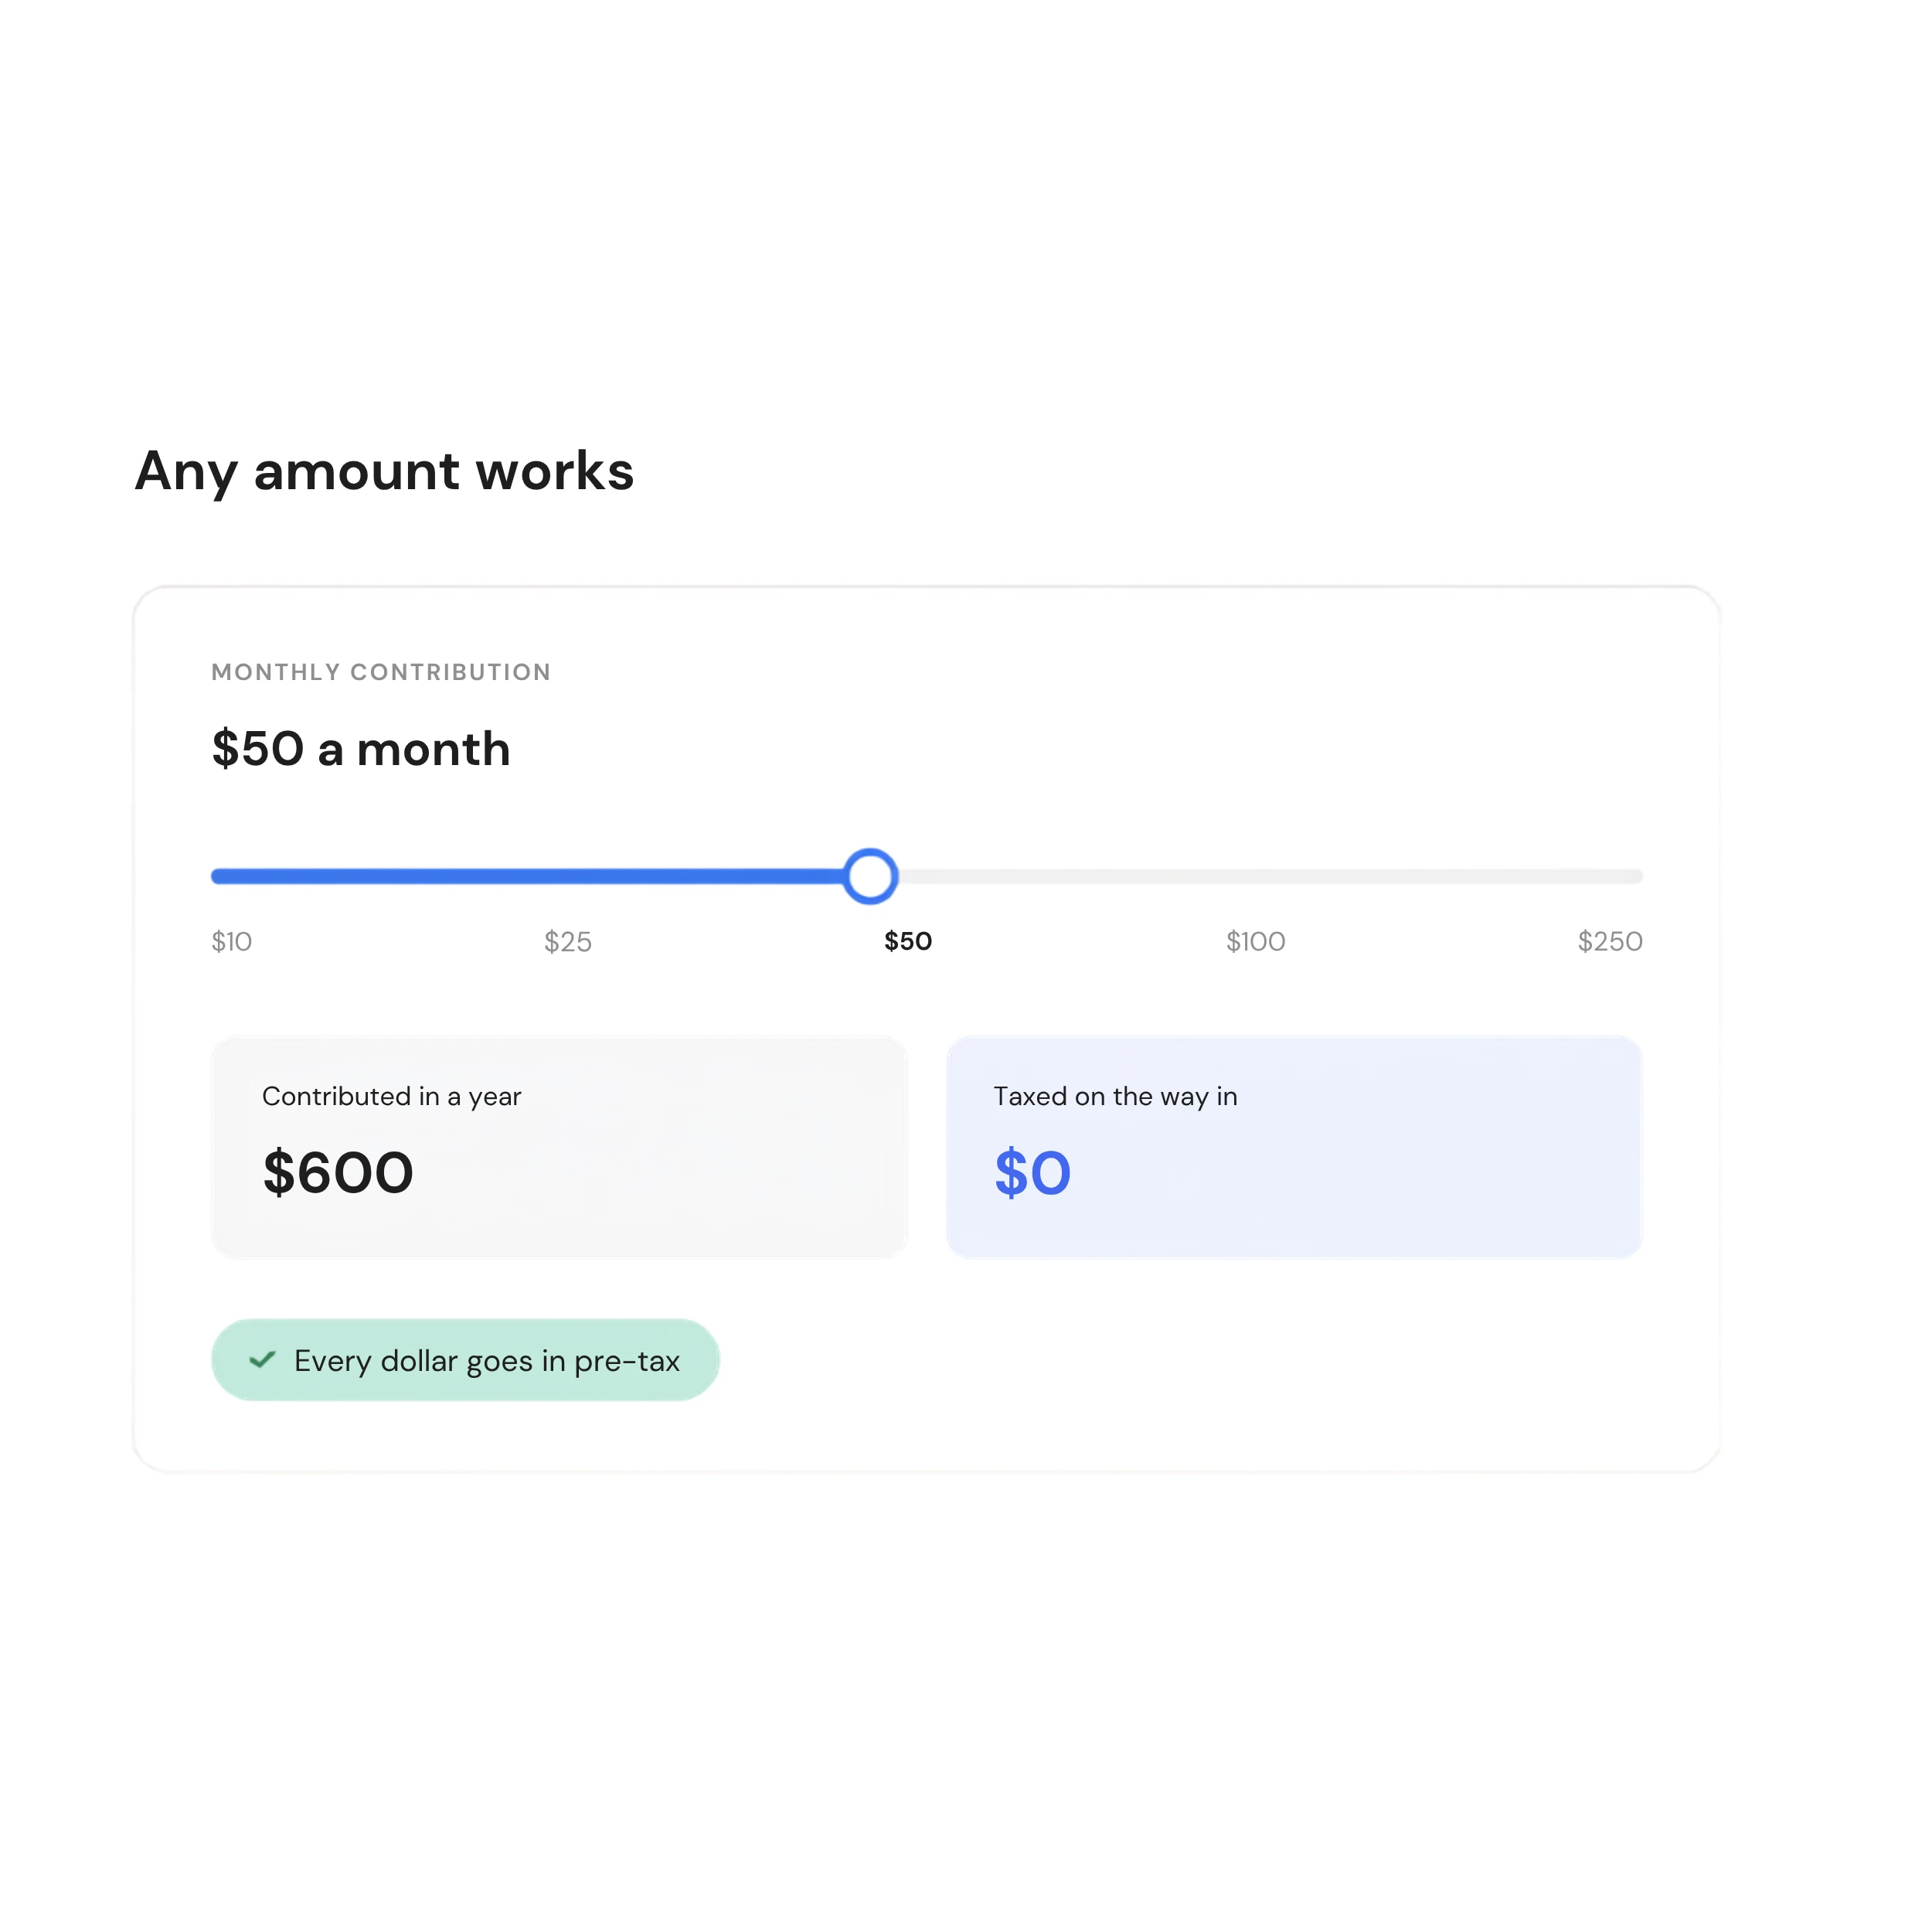
Any amount adds up. Every dollar you contribute is pre-tax, so you save on the taxes you'd otherwise pay on that money, whatever your bracket and whatever you're able to set aside.
The balance carries forward. Unspent dollars stay yours and keep growing, so year two starts ahead of year one instead of back at zero.
It compounds over time. Paying for care with tax-free HSA dollars adds up to more over the years than paying with taxed income.
Even a little adds up. Set aside $50 a month and you're contributing $600 a year, all of it pre-tax. That's real tax savings on money you were going to spend on care anyway, plus whatever's left over keeps growing instead of disappearing.
SIDE BY SIDE
What changes with a Lively HSA
Paying through an HSA changes where that money ends up. Here's what the difference looks like.
The Breakdown | Without an HSA | With a Lively HSA |
|---|---|---|
Money set aside for care | Paid with taxed income | Paid with pre-tax dollars |
Tax treatment | Fully taxed | Tax-free in, growth, and out for care |
Tax saved | $0 | A percentage of every dollar, based on your bracket |
Unspent funds at year end | Lost or taxed elsewhere | Roll over, stay invested |
This is why the difference is easy to miss year to year: the tax savings never show up as a bill, so there's nothing prompting a comparison. Looking at the numbers directly is what makes the value clear.
THE BENEFITS
What it does for you
Beyond the tax math, an HSA solves things people weigh most when choosing a health account, and it's the only one that's tax-free going in, growing, and coming out for care.
One thing matters most to anyone who's dealt with an FSA's use-it-or-lose-it deadline: an HSA works the opposite way, unspent money stays and keeps growing instead of disappearing every December. Here's how the rest breaks down.
Pay less on care now
Contributions are tax deductible, so you're spending pre-tax dollars on the doctor visits, prescriptions, and dental work you'd pay for anyway.
Never lose what you don't spend
Funds roll over year to year. There's no use-it-or-lose-it rule, so nothing you save is at risk of disappearing in December.
It turns into a retirement account at 65
After 65 you can use the money for anything, not just health, and simply pay income tax, exactly like a traditional IRA.
ELIGIBILITY
Is an HSA worth it for you?
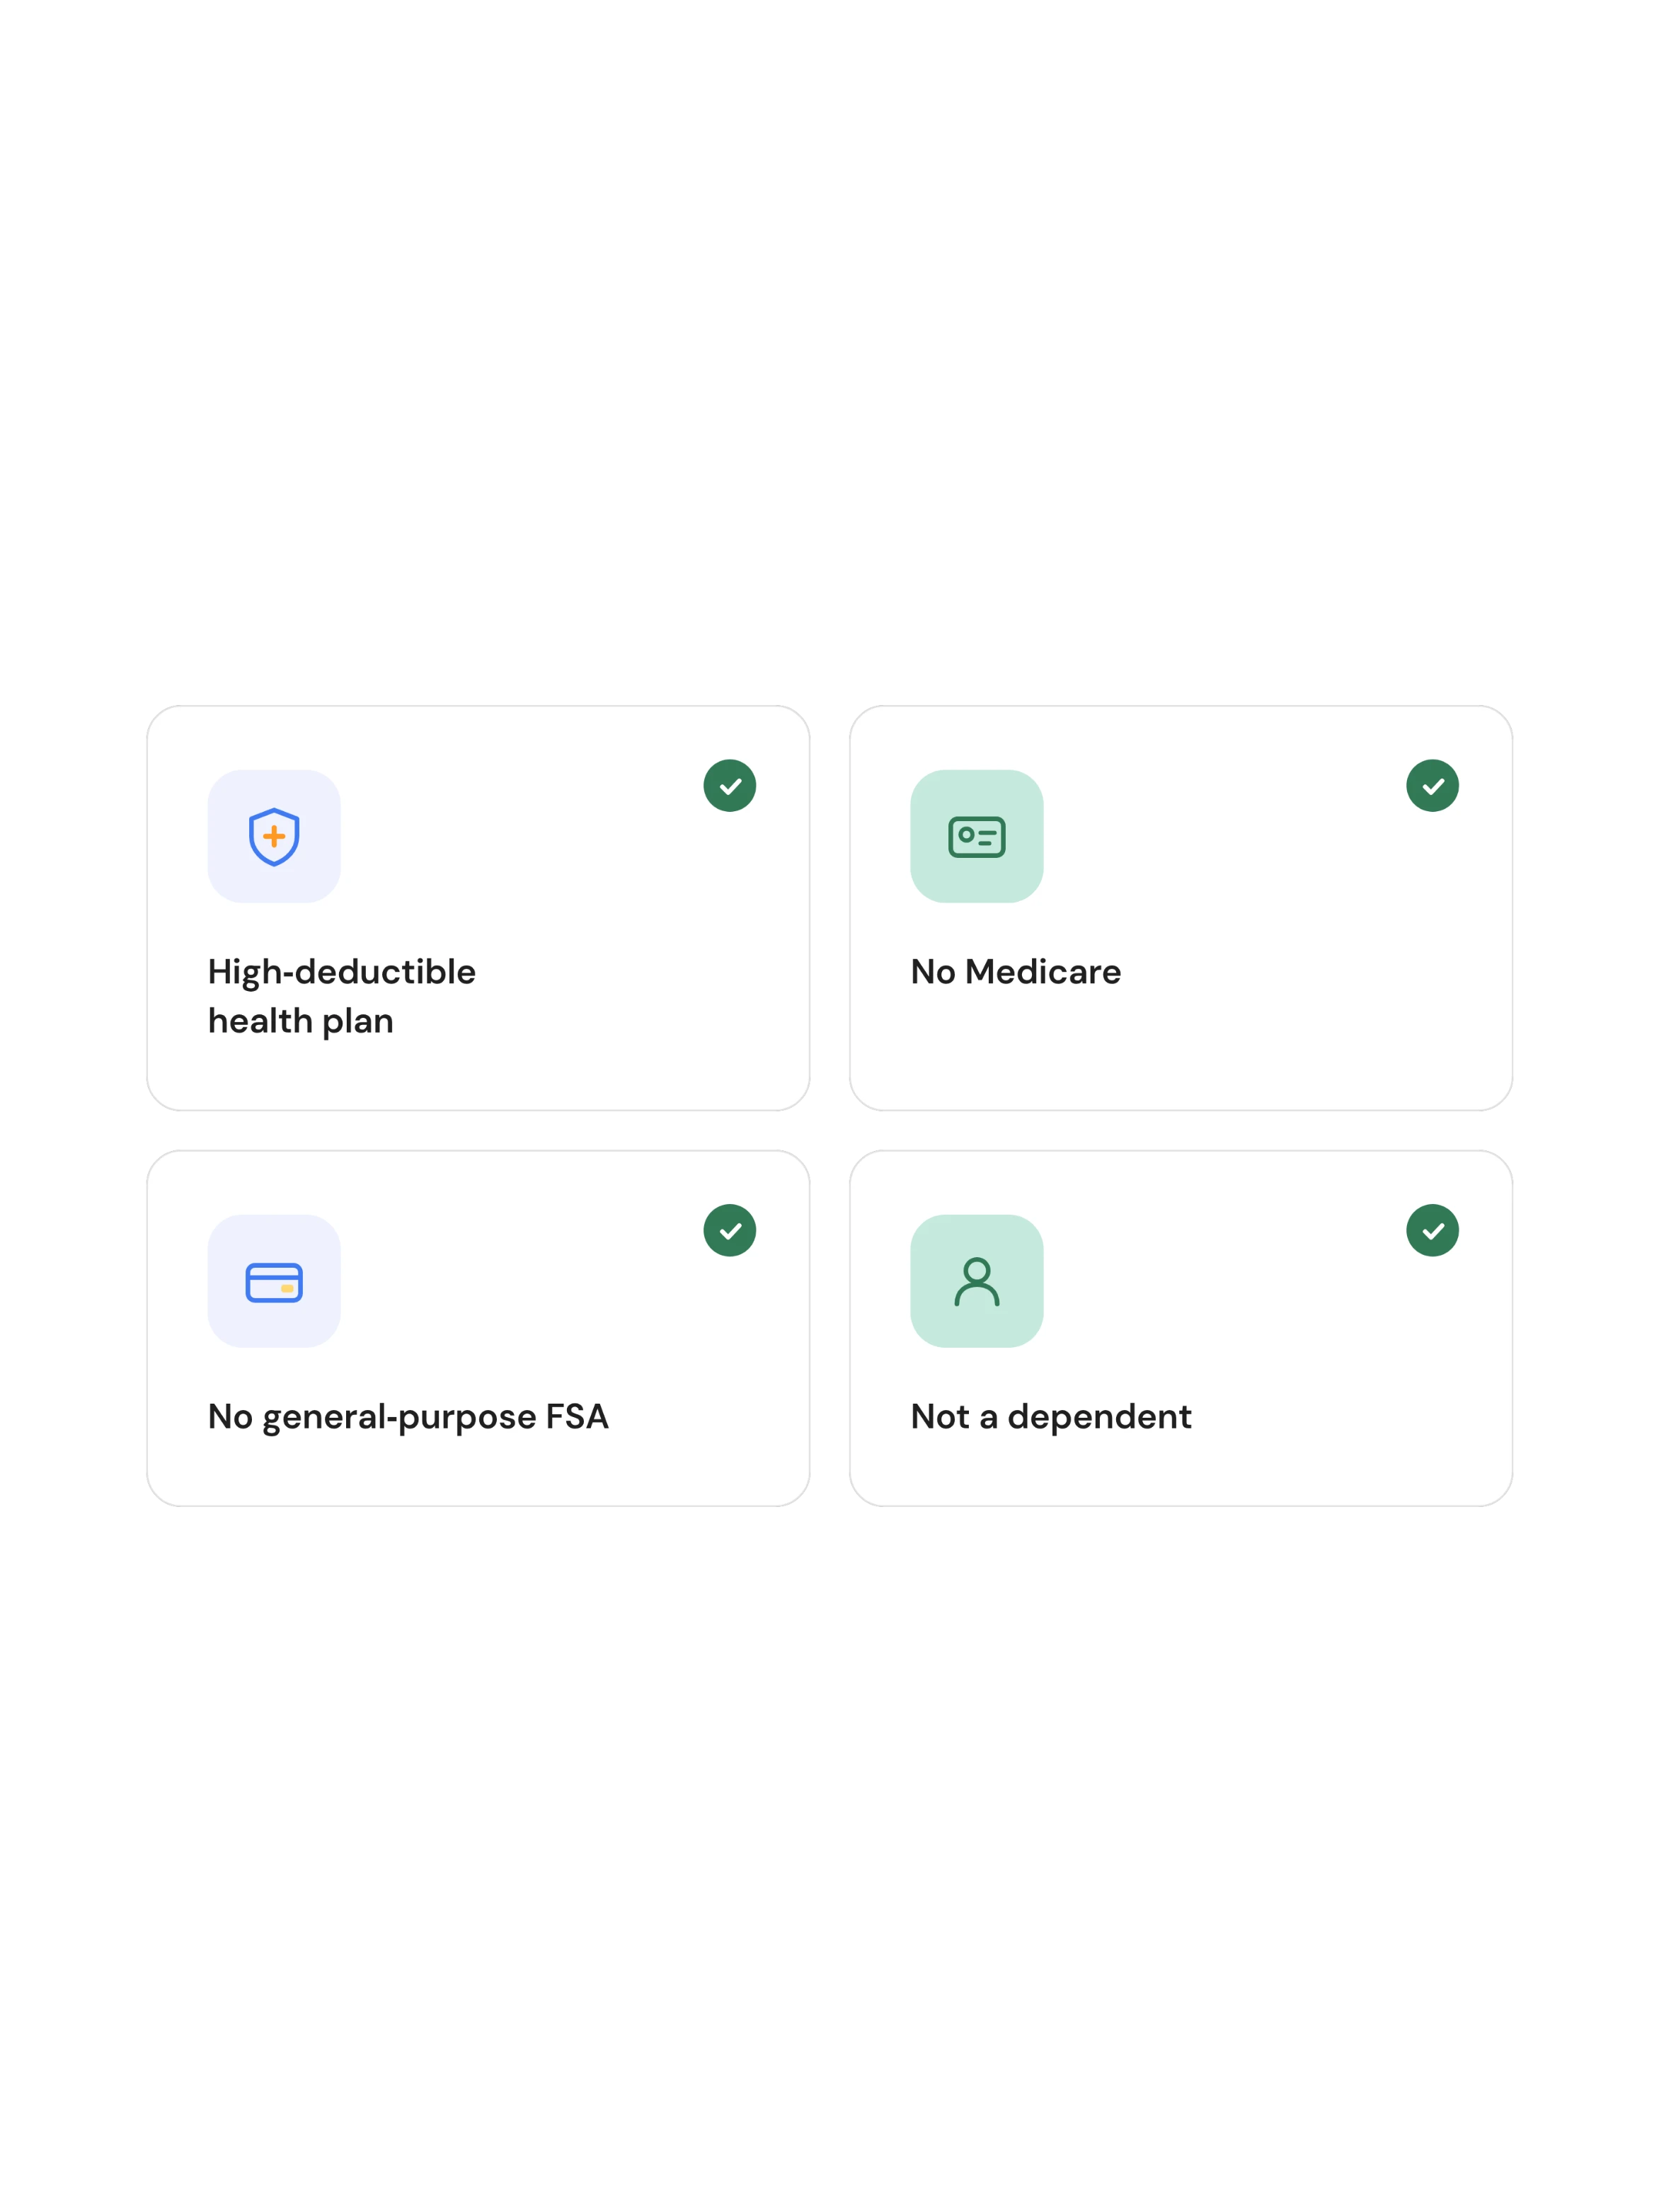
You don't need a finance background or a specific income to make an HSA work for you, just a plan that fits a few requirements. Here's a quick way to check if yours does.
Covered under a high-deductible health plan
Not enrolled in Medicare
Not covered by a general-purpose FSA
Not claimed as someone else's dependent
For 2026, you can contribute up to $4,400 as an individual or $8,750 for a family, plus an extra $1,000 if you're 55 or older. There's no minimum, so you can start small and adjust as you go.
GETTING STARTED
Simple to open, simple to run
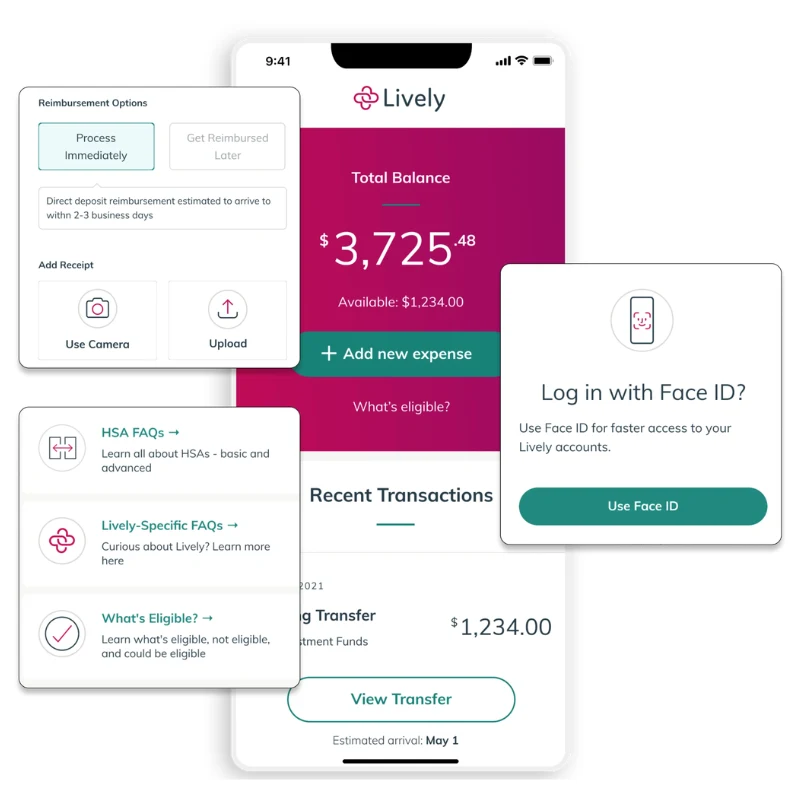
Setup and complexity are the two things people worry about most with a new account. Lively is built so neither one applies here. Setup takes minutes and the account runs itself from there.
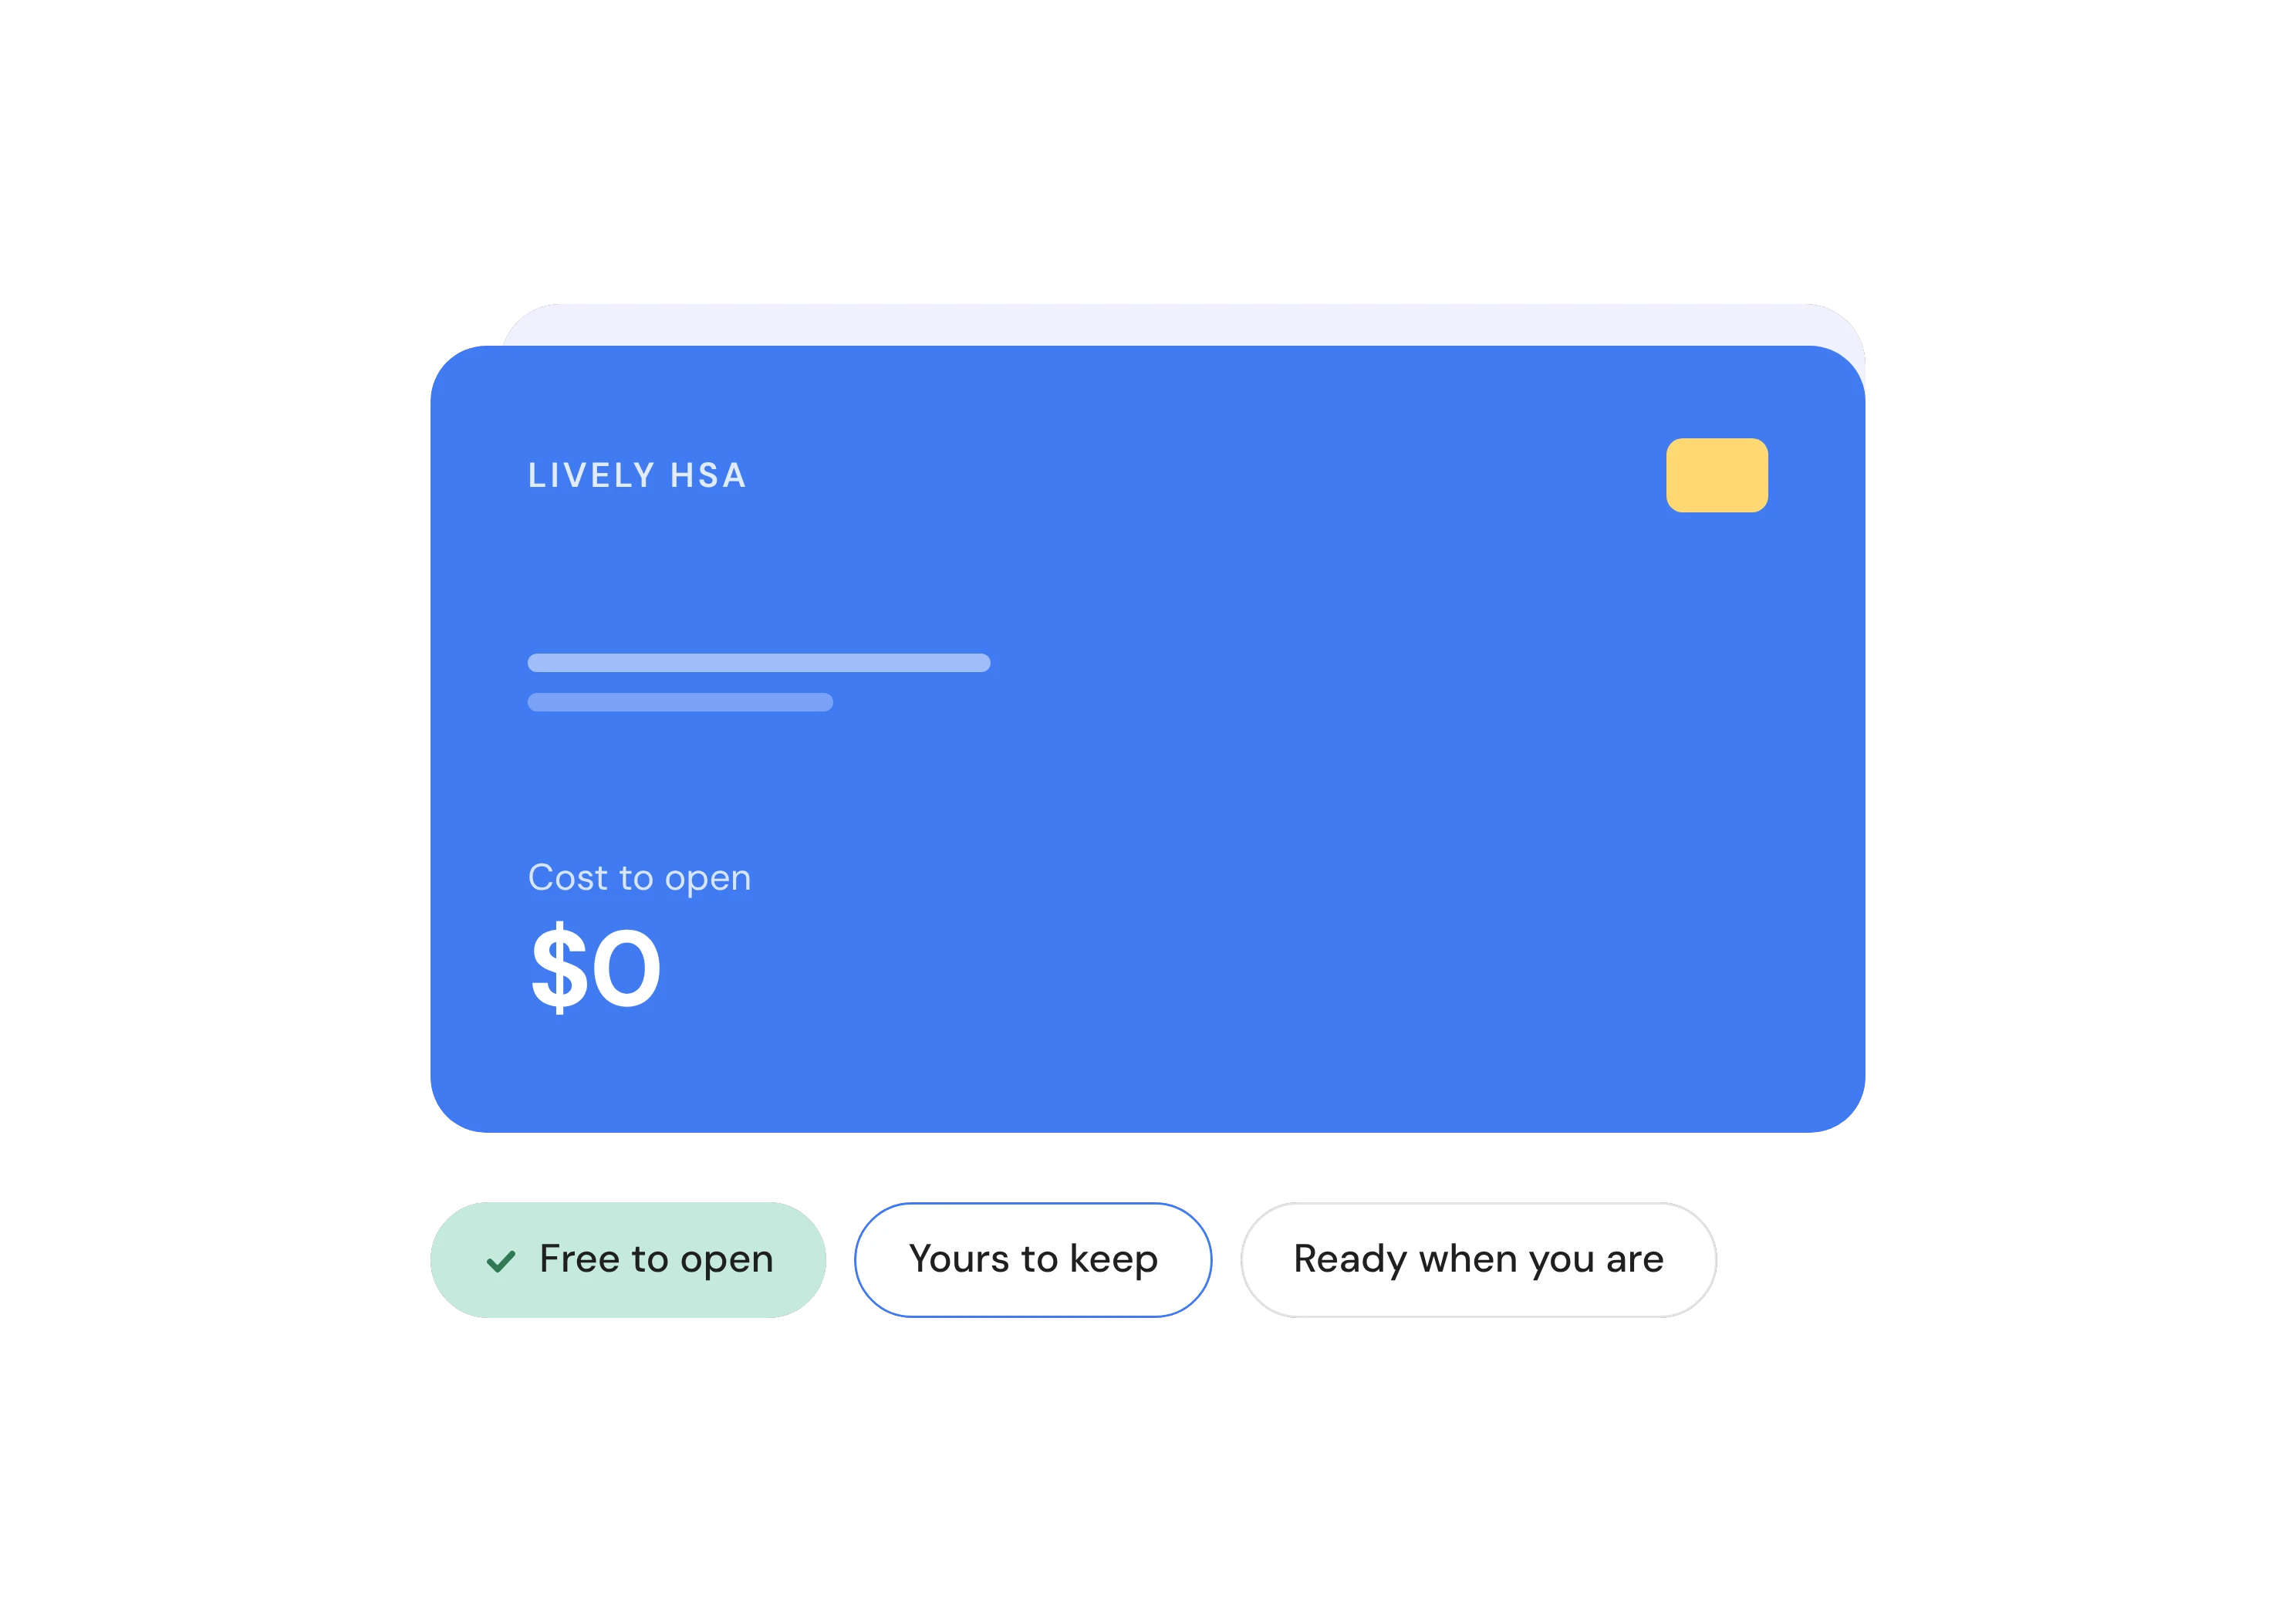
Free to open, with no hidden fees to track
Fully paperless from the first step
Managed entirely from your phone
No minimums to get started
An account that's simple to manage is one you'll actually keep using, which is what makes it valuable over time, and part of why ease of use matters as much as the tax benefit.
Choosing a provider
Why open yours with Lively
Once you've decided an HSA is worth it, the account you choose determines how much of that value you actually keep. Lively pairs straightforward pricing with real deposit protection and a fully paperless setup you manage from your phone, so more of your money works for your health and less gets lost to fees or hassle.
Transparent pricing
No hidden fees. What you see is what you pay.
FDIC-insured account
Your money is protected and secure.
Seamless management
100% paperless, run entirely from your phone.
Open your Free Lively HSA
An account for now and later
An HSA is one account that lowers your taxes now and builds a health fund for later. With Lively, it's free to open and easy to manage from day one. It's ready whenever you are.
RESOURCES
HSA Resources
From in-depth guides to savings calculators to our What's Eligible search, these tools cover the questions that come up before and after you open an HSA.
Learn More
Lively Individual HSA
Take a closer look at how a Lively HSA works, from opening your account to investing what you save.

GUIDE
HSA Guide
Everything you need to know about how HSAs work, who qualifies, and how to make the most of yours.

Calculator
HSA Calculator
See how much you could save with an HSA, including your payroll tax benefit.
Compare
Compare HSA Providers
Smart investing options, simple tools, and support when you want it. See how Lively delivers.
Calculator
Compare Plans
Project your yearly costs under two health plans and see which one saves you more money overall.